


SB News - September 2026
Government Offers Concessions On Proposed Trust Tax
The Federal Government has announced significant concessions to its proposed minimum tax on discretionary trusts, responding to sustained concerns from business groups, advisers and small business representatives about the potential cost and complexity of the reforms. Under the revised proposal, eligible discretionary trusts will be able to avoid the new minimum 30 per cent tax without undertaking a formal restructure, provided trustees elect to make fixed percentage distributions to nominated beneficiaries.
The change gives families and privately owned businesses another pathway for retaining their existing trust structures. However, greater tax certainty would come at the cost of some of the flexibility that akes discretionary trusts attractive in the first place. The measures remain in draft form and may change before becoming law.
The policy backdrop
The proposed trust tax formed part of the broader tax reform package announced in the May 2026 Federal Budget, alongside changes to capital gains tax and negative gearing. From 1 July 2028, a minimum 30 per cent rate is proposed to apply to income from discretionary trusts that falls within the new regime. The Government says the measure is intended to better align the tax paid on trust income with the rates paid by employees.
The Government has stated that fewer than 10 per cent of Australia’s 2.7 million active small businesses are expected to be affected in any given year. That could still have a meaningful impact on many established families and businesses, particularly those that have used discretionary trusts for commercial, asset protection, succession and family planning purposes over many years.
These are not inherently tax avoidance vehicles. Distributed income is generally taxed in the beneficiary’s hands at their applicable rate, while income retained within a trust may already be taxed at the highest marginal rate. The Government’s concern is more specifically directed at arrangements that distribute income among beneficiaries in a way that reduces the overall tax rate below the proposed 30 per cent minimum.
Concerns with the original proposal
The central practical concern was that some trusts would need to restructure to avoid the new tax.
Moving business, property or investment assets out of a trust can trigger capital gains tax, income tax, stamp duty, legal costs, valuation expenses and changes to existing financing arrangements.
The Commonwealth proposed expanded rollover relief for three years from 1 July 2027 to assist taxpayers restructuring out of a discretionary trust. However, stamp duty is imposed by state and territory governments. Without corresponding concessions, transferring certain assets into a new structure could still prove expensive.
The new election is intended to address this concern by allowing eligible trusts to remain legally intact while changing how they are treated for tax purposes.
What has now changed?
Under the exposure draft, eligible discretionary trusts existing at the commencement of the new regime would be able to elect to make fixed distributions to beneficiaries nominated in advance.
Those beneficiaries could include individuals, companies or other trusts capable of benefiting under the trust deed. There would be no limit on the number of beneficiaries initially nominated.
Rather than exercising broad discretion each year, the trustee would distribute income and capital among those beneficiaries in predetermined percentages. Each beneficiary would then be taxed at their applicable personal or company tax rate. Provided the trust complies with the election, it would be exempt from the proposed minimum tax.
Because the election would apply for tax purposes without changing the trust’s legal structure or ownership of its assets, the Government expects that it would not result in state or territory stamp duty. This gives trustees an alternative to transferring assets into a company, fixed trust or another structure solely in response to the proposed tax.
Greater certainty, but less flexibility
The trade-off is reduced discretion.
Once beneficiaries are nominated and percentages fixed, the trustee would have less capacity to adjust distributions in response to changing business income, family circumstances or beneficiary needs. Nominated beneficiaries could generally be added or changed only following certain events, such as the death of a beneficiary or a family breakdown. While the trustee could revoke the election, doing so may expose future trust income to the minimum tax.
Separately, the election would be automatically revoked if the trustee made a distribution inconsistent with the elected arrangement. In that event, the trustee could be taxed at the highest marginal rate, together with the Medicare levy, for the financial year in which the breach occurred.
Annual distribution resolutions, accurate records and appropriate professional advice would therefore become particularly important for trustees choosing the new regime.
Will the concession suit your trust?
The concession will not suit every trust. Variable income and the ability to respond to changing circumstances are among the principal reasons many families and businesses use discretionary trusts. Committing to fixed percentage distributions could undermine that flexibility, particularly for businesses with volatile profits or evolving family involvement. The election is likely to be more workable for trusts with a stable beneficiary group, predictable income and an established distribution approach. Even then, trustees should consider whether the arrangement is likely to remain appropriate as family circumstances, tax settings and succession plans change over time. The decision requires more than comparing headline tax rates.
Charitable and community distributions
Charitable trusts, together with trust distributions to registered charities and deductible gift recipients, would be excluded from the proposed minimum tax. The exclusion would also extend to distributions made to certain other income tax exempt entities, including sporting clubs and community organisations, up to a cap that is still to be determined through consultation.
This is intended to ensure the proposed tax does not unintentionally discourage philanthropy or reduce the funding available to charitable, sporting and community organisations.
What does this mean for bucket companies?
A corporate beneficiary, commonly known as a bucket company, could be included among the beneficiaries nominated under the new election. This suggests existing bucket company arrangements may continue to be available under the fixed distribution regime, with the company’s predetermined share of trust income taxed under the ordinary company tax rules rather than being subject to the trustee-level minimum tax.
However, the strategy would become significantly less flexible because both the nominated beneficiaries and their distribution percentages would generally need to be fixed in advance, with only limited scope for later changes.
The contrast with remaining in the default minimum tax regime is important. Under the exposure draft, non-corporate beneficiaries may be entitled to a credit for tax paid by the trustee, whereas corporate beneficiaries would not receive an equivalent credit. In many circumstances, this could result in trust income being taxed first at the trustee level and then again in the company, making traditional bucket company strategies materially less attractive for trusts that do not make the fixed distribution election.
Other excluded structures and income
The Government has confirmed that several other trust types and income categories will sit outside the proposed minimum tax. These include special disability trusts, complying superannuation funds, and deceased estates, alongside the charitable exclusions outlined above. Certain primary production income and income relating to vulnerable minors will also receive separate treatment.
The exposure draft proposes a new definition of a fixed trust so that commercial structures without material discretionary features are not inadvertently captured. These structures are expected to include widely held trusts, managed investment trusts, bare trusts and employee share trusts. Further administrative and integrity provisions are expected to be introduced through later tranches of legislation.
Restructuring remains an option
Trustees can still choose to restructure rather than elect into the new regime.
For some families and businesses, a company, fixed trust or another ownership structure may provide a better long term outcome once the rules are settled. However, restructuring should not be assessed solely on tax grounds. It can affect asset protection, estate planning, succession, control, financing arrangements and the ability to admit future owners or beneficiaries.
While the proposed Commonwealth rollover relief may reduce certain federal tax consequences, state and territory stamp duty could remain a substantial barrier.
What happens next?
Consultation on the exposure draft closes on 18 September 2026. Implementation will be finalised through further tranches of legislation, including additional administrative and integrity measures where required. Some important aspects of the regime may therefore remain unsettled after the current consultation period closes.
The financial impact of the latest concessions has not yet been disclosed and is expected to be addressed through the Government’s normal Budget reporting process. For now, trustees should understand the potential implications but avoid making irreversible structural decisions based solely on the current announcement. The final legislation, supporting regulations and administrative guidance will ultimately determine which trusts are affected, how the election will operate in practice and what compliance obligations will apply.
There is no immediate requirement to restructure or make an election. Stanford Brown will continue to monitor the proposed reforms as they progress through consultation and Parliament. Once the final rules are known, we will work with affected clients and their accounting and legal advisers to assess the implications for their structures and determine whether any action is appropriate.
By Vincent O’Neill, CEO
Treasury Yields Surge to Multi-Year Highs as Warsh Signals Inflation Fight Not Over
The US 10-year Treasury yield reached 4.81% earlier this week, its highest level since November 2023, before easing to around 4.77% on 3 September. The 30-year yield remains above 5.2%. Across the curve, yields are materially higher than a year ago, with the 10-year up more than 50 basis points over the past twelve months. The move has formed part of a broader global bond sell-off as investors weigh persistent inflation, heavy debt issuance and the prospect of further monetary tightening.
The latest leg higher followed Fed Chair Kevin Warsh’s keynote address at the Jackson Hole Symposium on 28 August. Reuters reported that Warsh signalled rates may need to rise if inflation fails to make clearer progress, while explicitly stepping back from the forward guidance framework used by his predecessors. “We should not indulge a regime in which market participants are looking primarily to the Fed for their next trade,” he said. While summer inflation readings were better than expected, Warsh said they did not indicate that underlying trends had meaningfully improved, reaffirming the 2% PCE target as what he called a “firm, fixed target.” Markets responded by materially increasing the probability of a near-term rate hike. As of 2 September, futures markets were pricing around a 66% chance of a 25 basis point increase at the September meeting, up from around 40% the week prior. Fed Governor Barr separately said he would support a hike if inflation did not ease.
Treasury had already moved to increase liquidity support at the long end of the market, announcing that maximum buyback operations would at least double to $4 billion from 9 September. Treasury Secretary Bessent pushed back on fears over US debt market strains, defending the expanded programme as a liquidity measure. The initial decline in long-end yields that followed the announcement proved short-lived.
Several factors have contributed to the broader rise in yields. Persistent inflation and elevated oil prices from ongoing Middle East tensions have pushed expectations for further Federal Reserve tightening higher, while concerns over large fiscal deficits and increased government borrowing have weighed particularly on longer-dated Treasuries. Heavy corporate issuance linked to investment in AI and data-centre infrastructure has added to the supply of debt competing for investor demand. New York Fed President John Williams explicitly argued this week that the move was not primarily being driven by inflation fears, but by stronger economic activity and AI and data-centre investment, offering a counterpoint to inflation-focused explanations for the rise.
Friday’s non-farm payrolls report is a key input into the September decision. The ADP survey released this week pointed to a further slowdown in private-sector employment growth in August, providing one data point that could argue against an immediate hike. The Federal Open Market Committee will also have inflation and other economic data to consider before its September meeting.
By Joey Mouracadeh, Senior Investment Director
Bathla Collapse Puts Australian Private Credit to the Test
Bathla Group, one of western Sydney’s largest residential property developers, entered voluntary administration on 25 August with debts reported at approximately $3.6 billion, much of it owed to private credit lenders, leaving 2,000 homes mid-construction and 15,000 more planned dwellings in limbo.
Teneo Financial Advisory Australia was appointed voluntary administrator of key entities including parent company Universal Property Group. Teneo said it needed approximately $20 million to continue near-term operations and around $40 million to keep construction running through Christmas, with the group reported to have essentially no cash for wages or supplier payments. The first creditors meeting is scheduled for 4 September. Founder Bhart Bhushan attributed the collapse to softening sales, changes to negative gearing and capital gains tax announced in the May 2026 federal budget, and rising construction costs. Bathla had sought forbearance from lenders as early as July.
Nearly 50 private credit firms are exposed, according to people familiar with the matter cited by Bloomberg. PAG, CVS Lane Capital Partners and Centuria Bass are among the largest, having collectively extended more than $1 billion to the developer, with PAG alone providing more than $300 million. Other lenders include Ray White Capital, La Trobe Financial, MaxCap, Wingate, Balmain and Trilogy. Balmain said it expected to fully recover its loans. La Trobe said its exposure amounted to approximately $38.1 million, around 0.15% of assets under management, and confirmed it would not restrict redemptions. PAG and Wingate declined to comment.
Bathla’s collapse has coincided with, and intensified scrutiny of, a broader tightening in liquidity across Australian private credit funds. Centuria Bass had frozen approximately $670 million in redemptions in mid-August after investor withdrawal requests increased following concerns about its Bathla exposure. MA Financial announced on 25 August that it was capping redemptions from its $2.3 billion MA Secured Real Estate Income Fund at 1% of funds under management per month for at least three months, saying it had no direct Bathla exposure and describing the cap as a proactive response to broader market conditions. 360 Capital placed its Mortgage REIT into a trading halt pending clarification of its own exposure. Merricks and Longreach Credit have also restricted redemptions, according to ABC News.
ASIC Chair Sarah Court said this week the sector was facing its first real test and described current events as the first significant cracks in the market, adding that the regulator was closely scrutinising developments.
The episode has drawn attention to a structural feature of the asset class. Private credit funds generally hold loans that are not readily tradeable and may be difficult to sell quickly, while some offer investors monthly or quarterly access to capital. That structure can come under pressure when withdrawal requests increase at the same time as borrowers encounter difficulty. Exposures and likely outcomes vary significantly between the lenders involved, with several having already said they expect little or no loss. ASIC said it would continue active surveillance. The creditors meeting on 4 September is expected to provide the next material update.
By Joey Mouracadeh, Senior Investment Director
Responsible Investing at a Crossroads?
Over the past two years, environmental, social and governance investing has entered a more challenging phase. The optimism that characterised the early years of responsible investment, when decarbonisation appeared to offer a relatively straightforward alignment between financial returns and positive environmental outcomes has been replaced by a more complicated reality shaped by war, energy insecurity, and the extraordinary growth of artificial intelligence.
Escalating geopolitical tensions have forced ethical investors to reconsider some long held assumptions. Russia’s invasion of Ukraine, conflict in the Middle East and growing strategic competition between the United States and China have elevated national security, resilient supply chains and energy independence as investment priorities. Defence companies, previously excluded from many responsible portfolios, are increasingly viewed by some investors as supporting democratic security and geopolitical stability, particularly across Europe where many countries’ have committed to increasing spending.
Energy security has undergone a similar reassessment. Governments that had focused heavily on accelerating the transition away from fossil fuels have faced the practical challenge of maintaining reliable and affordable energy supplies. Natural gas, nuclear power and domestic energy production have consequently returned to the centre of policy discussions. For responsible investors, the question is no longer simply whether a company produces fossil fuels, but whether it is credibly managing its emissions, investing in transition technologies and contributing to a more secure energy system.
The election of Donald Trump further altered the global policy environment. Since returning to office in January 2025, his administration has prioritised domestic energy production, reduced environmental regulation and challenged state-based climate policies. At the same time, the global build-out of AI infrastructure is creating an energy challenge that cannot be ignored. Data centres require enormous quantities of electricity and water to power and cool increasingly sophisticated computing systems. The International Energy Agency expects global data-centre electricity consumption to approximately double from 485 terawatts/hour in 2025 to 950 terawatts/hour by 2030, while consumption from AI-focused facilities could triple. Renewables are expected to meet a portion of this growth, but natural gas, coal and nuclear generation will also be required, particularly where grid reliability and speed of connection are critical.
These developments have affected investor behaviour. Global sustainable funds attracted approximately US$38 billion in 2024, but this was substantially below earlier growth rates. In 2025, the sector recorded approximately US$84 billion in net outflows, the first annual outflow since Morningstar began tracking the global sustainable fund universe in 2018. Flows improved modestly during 2026, with sustainable funds excluding China attracting US$3.7 billion in the June quarter.
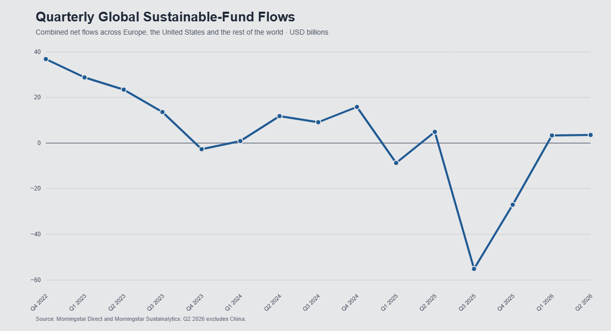
This moderation suggests that investors are becoming more discerning and increasingly unwilling to accept broad sustainability labels without evidence of competitive returns, credible outcomes and disciplined portfolio construction. As a firm, we recognise that responsible investing is inherently personal and that no single portfolio can accommodate every investor’s individual preferences, values and ethical beliefs. Therefore when constructing responsible investment portfolios, we apply broad, industry-wide limits to investment in, tobacco and controversial weapons. These limits provide a practical and consistent baseline or catch-all framework designed to address the concerns most commonly shared by responsible investors. Where clients have more specific ethical requirements, advisers can amend these portfolios and apply additional constraints to create a more bespoke solution. This allows us to maintain a robust and repeatable investment framework while retaining the flexibility needed to reflect an individual client’s preferences.
By Joseph Nakhoul, Investment Research Analyst
Dubai Finally Put to the Test!
For years, Dubai has attracted investors and businesses through its favourable tax regime, strong rental yields and growing status as an international financial hub. As global banks, asset managers and family offices began to expand their presence, demand for residential property became increasingly connected to the city’s broader economic ambitions. Additionally, Dubai also offered a sense of security, with investors believing it would remain protected from conflict elsewhere in the Middle East. Over the past six months, the war involving the United States, Israel and Iran has tested that thesis, forcing investors to reconsider how much of Dubai’s property boom and financial appeal rested on its reputation for security.
When hostilities escalated, Iranian strikes against Gulf states challenged the assumption that the United Arab Emirates could remain insulated from regional conflict. Dubai’s initial response was not an immediate collapse in property prices, but a withdrawal of liquidity. Buyers paused and transaction volumes declined. This sequence is typical of property markets confronting a sudden shock: activity ordinarily weakens before valuations begin to adjust. ValuStrat’s citywide residential index declined from 243.4 points at the end of February 2026 to 219.2 to the end of July 2026, a fall of approximately 10%. The correction was sharp, with values falling 5.9% in March, before moderating to only 0.3% in July. This slowing rate of decline suggests that the initial shock subsided, although renewed military exchanges demonstrate that geopolitical risk remains.
The correction arrived when Dubai was approaching a difficult stage of its property cycle. Prices had risen rapidly after the pandemic, development accelerated and off-the-plan sales represented a substantial share of activity. A large apartment pipeline was approaching completion as foreign buyers became cautious. The war did not create these vulnerabilities but exposed them, particularly in investor heavy apartment districts which are much more sensitive to tighter liquidity. At the other end of the market, scarce luxury property remains remarkably resilient. Sales of homes above US$10 million reached a record US$5.1 billion during the first half of 2026. Wealthy buyers continue to value Dubai’s tax structure, connectivity and financial infrastructure. For these individuals, the city may still compare favourably with other global centres, even after allowing for a higher geopolitical risk premium.
The fundamental question raised by the conflict is whether Dubai’s reputation for security has been permanently damaged, making geopolitical risk a more important consideration in asset valuations, particularly for emerging market managers. These managers have been forced to navigate this uncertainty, especially those that had Dubai listed real estate exposure within their portfolios prior to the conflict and have subsequently experienced a decline in returns. For prospective investors, however, this repricing may create investment opportunities where market pessimism has exceeded reality. This is where experienced managers with dedicated regional offices can offer an advantage. Local teams can assess business activity, population movements and investor confidence firsthand, helping determine whether security concerns represent a structural change or a temporary disruption amplified by news headlines.
By Joseph Nakhoul, Investment Research Analyst
Latest Podcast
SB Talks: A Goldilocks Moment for Markets?
In this episode of SB Talks, Vincent O’Neill and Chief Investment Officer Nick Ryder explore whether the US economy is entering a “Goldilocks” phase, with moderating inflation, softer employment data and exceptionally strong corporate earnings easing pressure on the Federal Reserve. They discuss what the latest US and Australian inflation figures mean for interest rates, why markets have become more optimistic about the outlook for central banks, and the key risks that remain. Closer to home, they examine the RBA’s latest decision, the early themes emerging from reporting season, and what weakening housing market activity and slowing mortgage demand could mean for the Australian economy in the months ahead.
Listen on Apple Podcasts
Watch on Youtube: